Most people take out a loan and keep their savings at the bank where they have their current account. We checked what that costs them, using data from 12 banks and savings banks on the same day, 3 October 2026. The differences are larger than most people expect.
Key findings
- Mortgages: on a €150,000 fixed-rate loan over 20 years, the gap between the cheapest and the most expensive bank was more than €14,000, including all costs.
- Deposits: for €10,000 deposited for one year, the best bank paid €250 of interest and the two worst €90 each. One of them is Slovenia’s largest bank.
- The advertised rate misleads: for consumer loans, the gap between the advertised rate and the real cost (APR) was as much as 2.58 percentage points at one bank.
Mortgages: more than €14,000 difference
We compared a €150,000 loan over 20 years for an existing customer with a loan-to-value ratio of 75%, using regular offers without time-limited promotions. All costs paid to the bank are included: interest, the approval fee, the property appraisal, and the monthly fee for the loan and for the account the bank requires. Because insurance premiums are not counted, we used the rates that do not require life insurance.
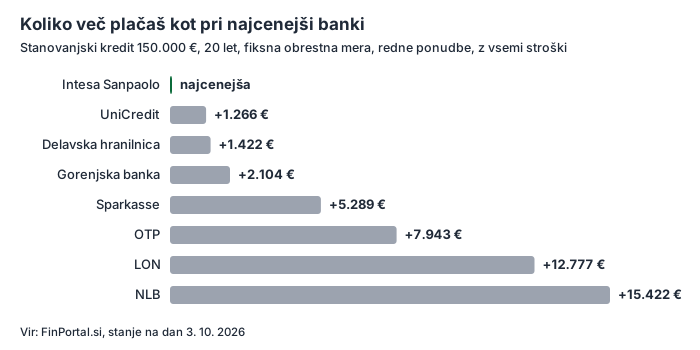
Fixed rate (8 banks):
| Bank | Interest rate | APR | Monthly payment | Total paid |
|---|---|---|---|---|
| Intesa Sanpaolo* | 3.45% | 3.64% | €875 | €210,202 |
| UniCredit | 3.55% | 3.72% | €879 | €211,468 |
| Delavska hranilnica | 3.50% | 3.73% | €879 | €211,623 |
| Gorenjska banka | 3.60% | 3.77% | €881 | €212,306 |
| Sparkasse | 3.80% | 3.94% | €896 | €215,490 |
| OTP banka | 3.90% | 4.08% | €908 | €218,145 |
| LON | 4.10% | 4.37% | €924 | €222,979 |
| NLB | 4.30% | 4.49% | €939 | €225,623 |
* Intesa Sanpaolo sets its approval fee when the contract is signed and does not publish it, so it is not included. The actual total may therefore be somewhat higher.
The gap between the cheapest and the most expensive bank is €15,422, about €64 a month for the full 20 years. Even if Intesa’s approval fee pushed it behind UniCredit, the gap would remain above €14,000.
Variable rate (11 banks):
For variable rates, banks use different EURIBOR values published on different days. To compare the banks’ prices rather than the publication date, we calculated all offers with the same EURIBOR plus each bank’s margin. The margin is the part of the rate the bank sets, and it stays the same for the whole loan. There are 11 banks because Addiko Bank does not offer housing loans.
| Bank | Margin | Interest rate* | APR | Monthly payment | Total paid |
|---|---|---|---|---|---|
| BKS Bank | 0.875% | 3.875% | 4.03% | €904 | €217,287 |
| Intesa Sanpaolo | 1.00% | 3.92% | 4.13% | €911 | €219,016 |
| LON | 1.10% | 4.02% | 4.28% | €918 | €221,494 |
| UniCredit | 1.20% | 4.12% | 4.31% | €924 | €222,230 |
| Sparkasse | 1.25% | 4.17% | 4.32% | €926 | €222,542 |
| Delavska hranilnica | 1.20% | 4.12% | 4.37% | €927 | €223,312 |
| OTP banka | 1.35% | 4.27% | 4.47% | €937 | €225,231 |
| DBS | 1.45% | 4.37% | 4.54% | €941 | €226,448 |
| NLB | 1.45% | 4.37% | 4.56% | €945 | €227,012 |
| Primorska hranilnica | 1.45% | 4.37% | 4.57% | €945 | €227,182 |
| Gorenjska banka | 1.60% | 4.52% | 4.73% | €954 | €229,847 |
* Calculated with the 6-month EURIBOR at 2.92% (September 2026 average) plus the bank’s margin. Under its price list, BKS Bank rounds EURIBOR up to 1/8% (to 3.00%), which is included. OTP banka is linked to the 3-month EURIBOR, so its comparison is by margin.
Margins ranged from 0.875% to 1.60%, which on this loan means a difference of €12,560, about €50 a month. BKS Bank has the lowest margin, but it rounds EURIBOR up, so its rate is 3.875% rather than 3.80%. Details like this are in the price list, so the small print is worth reading.
The differences are not down to the chosen example. With terms of 15 to 30 years, an 80% loan-to-value ratio or for non-customers, the gap between the cheapest and the most expensive bank ranged from €9,000 to €26,700.
Deposits: the best bank pays 2.8 times more
For a €10,000 deposit for 12 months, we took each bank’s best regular offer, without time-limited promotions. Where a bank pays a higher rate for deposits opened through online banking, we used that rate.
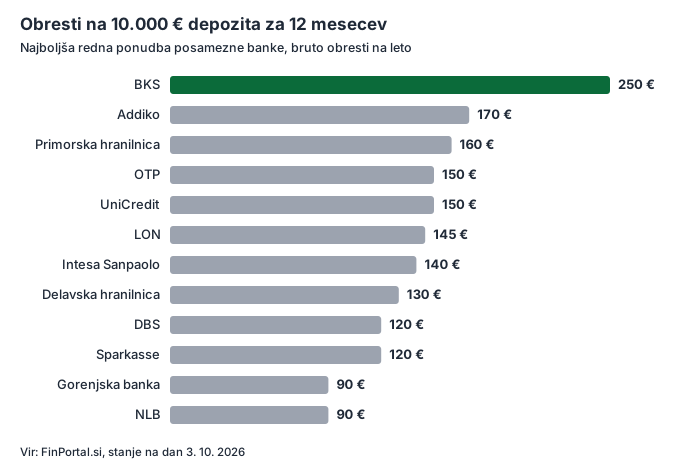
| Bank | Interest rate | Interest per year (gross) |
|---|---|---|
| BKS Bank | 2.50% | €250 |
| Addiko Bank | 1.70% | €170 |
| Primorska hranilnica | 1.60% | €160 |
| OTP banka | 1.50% | €150 |
| UniCredit | 1.50% (opened online) | €150 |
| LON | 1.45% | €145 |
| Intesa Sanpaolo | 1.40% | €140 |
| Delavska hranilnica | 1.30% | €130 |
| DBS | 1.20% | €120 |
| Sparkasse | 1.20% (opened online) | €120 |
| Gorenjska banka | 0.90% | €90 |
| NLB | 0.90% (opened online) | €90 |
On €10,000 the difference is €160 a year; on €50,000 it is already €800 a year. Slovenia’s largest bank, where many people keep their savings, came last together with Gorenjska banka, even when the deposit is opened online. In a branch, NLB offers only 0.70%.
Deposits are guaranteed up to €100,000 per depositor at every bank. For branches of foreign banks, such as BKS Bank, the home country’s guarantee scheme applies, which also guarantees up to €100,000. More in the article Deposit guarantee up to €100,000.
Consumer loans: the advertised rate is not the real price
For a €10,000 consumer loan over 5 years, the differences in total cost were smaller, up to €914. More instructive is how far the advertised rate can be from the real cost of the loan (APR), which includes approval and administration fees and any required account.
| Bank | Advertised rate | APR |
|---|---|---|
| Delavska hranilnica | 4.90% | 7.48% |
| LON | 5.50% | 8.05% |
| Intesa Sanpaolo | 5.30% | 7.36% |
A bank with a lower advertised rate can end up more expensive. Why that happens is explained in the article Same rate, different loan.
What this means for you
- Compare at least three banks before you sign a loan agreement or lock away your savings. It is the quickest saving you can make.
- Compare the APR, not the interest rate. The APR includes costs the advert does not show. Work it out in the APR calculator.
- For a variable rate, compare the margin. EURIBOR is the same for every bank; the margin is set by the bank and lasts for the whole loan.
- Check online opening. Some banks pay more for a deposit opened through online banking than in a branch.
- You do not have to keep your deposit at your own bank. You usually do not need to move your salary to open a deposit elsewhere, but check the terms, as some banks require an open account.
Current offers from all banks, updated daily, are in the mortgage comparison, consumer loan comparison and deposit comparison.
Methodology
- Data date: 3 October 2026. The data comes from banks’ official price lists and websites, which FinPortal.si collects every day. We also checked the key figures directly in the banks’ price lists.
- Mortgage: €150,000, 20 years, existing customer with salary paid into the bank, loan-to-value ratio 75%, regular offers without promotions and without mandatory life insurance. The total includes the payments, the approval fee, the appraisal (€300 where the bank does not publish its own) and the monthly fee for the loan and for the cheapest account the bank requires for the offered rate.
- Variable rate: calculated with a single 6-month EURIBOR of 2.92% (September 2026 average, source ECB) plus each bank’s margin; for BKS Bank with EURIBOR rounded up to 1/8%, as its price list specifies.
- Sensitivity: we repeated the calculations for 15, 25 and 30 years, an 80% loan-to-value ratio and non-customers. In every case the gap between banks stayed above €9,000.
- Consumer loan: €10,000, 5 years, existing customer, regular offers without mandatory insurance, the same rules for costs.
- Deposit: €10,000, 12 months, each bank’s best regular offer, including online opening, gross interest before tax.
- Banks covered: all 12 banks and savings banks tracked by FinPortal.si. Where a bank has no offer for a scenario, it is not in that comparison.
- Offers change, so the ranking can differ from day to day.
Details of how the data is collected are in the methodology.
Download the data
All figures from the study are available as a CSV file (opens in Excel; labels in Slovenian).
For the media: you may quote and use the data freely. Please credit FinPortal.si with a link to this study. For further calculations or other scenarios, write to info@finportal.si.
This study is for information only and is not financial advice.